Key Take Aways:

  • Choosing how to structure your annuity income is a critical decision.
  • It is not an either or decision between a Life and Living Annuity.
  • You can blend or use a combination of annuities.
  • It would benefit you to understand your annuity options and the implications of your choices.
  • This case study gives you a feel for how it can work for you.

Deciding how to structure and access the best income from your retirement nest egg? 

This analysis on blending annuity incomes is for you.

A Surprising Revelation

For anyone approaching retirement, one question tends to dominate: “Will my money last as long as I do?”

Traditionally your two main options of accessing a regular income in retirement are:

Living Annuity – Offers flexibility and control of your income but carries a higher risk of outliving your savings if you are not careful. You get to leave any remaining capital behind for beneficiaries.

Life (Guaranteed) Annuity – Provides income certainty as the income is guaranteed to be paid for the reminder of your life. The catch is that any unused capital cannot be left for your beneficiaries.

This can turn the decision making into a tug-of-war in your mind: the desire for flexibility and control versus the desire for certainty and a good night’s sleep.

But it does not have to be one over the other.

If you make the decision before retiring from your funds, you can make use of a combination of the two.

You may be pleasantly surprised by the findings.

The Analysis

If we analyze and compare these 3 options using a financial model, we can see exactly where the risks lie and how they can potentially be mitigated.

In the following case study we consider the 3 options:

(1) A 100% Living Annuity (LA)

(2) A 100% Guaranteed or Life Annuity (GA)

(3) A Blend of the two – 40% GA and 60% LA

Firstly, as with all models there are some key Assumptions that need to be made. Here is a summary of them:
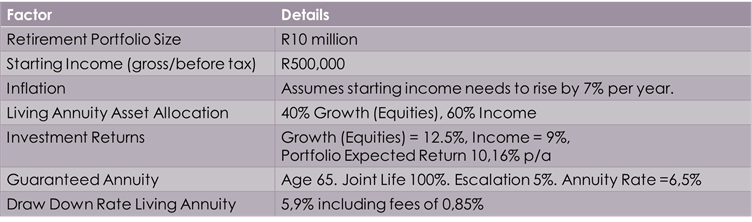
Assumptions for the blended annuity analysis by White Investments.

Comparison tables of the key findings:
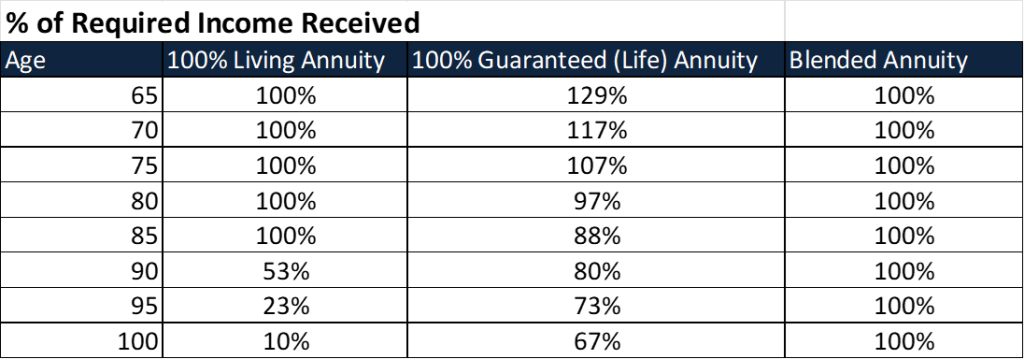
Percentage of required income received

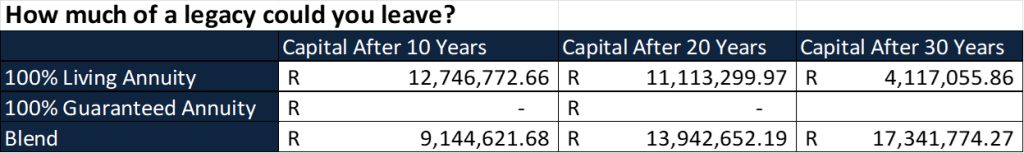
What about how much you can leave behind for beneficiaries

Please note the legacy values expressed above do not take into account inflation (nominal values). The real feel, or purchasing power, of the 20-year capital value,  if inflation was 7%, would be R2.8 million for the 100% LA and R3.6 million for the Blended option.

1. The Flexible Living Annuity can be a longevity trap

The 100% Living Annuity (LA) is attractive because it puts you in control. Your capital remains invested, giving you the potential for inflation-beating growth and the flexibility to adjust your income. However, this control comes with longevity risk, the danger of your money running out before you do.

In a high-inflation environment (modelled here at 7%), this risk is significant. The model shows the pure LA is projected to fully meet your expected income needs for 21 years.

For the first two decades, everything feels fine. After age 85 you reach your maximum LA cap of 17.5% of your portfolio, and your income falls quickly thereafter. By age 90, you are projected to cover only 53% of your income needs.

This is where the initial comfort of a flexible annuity can feel more like a trap, and there is little that can be done about it by that stage.

2. The Guaranteed Annuity's Hidden Risk: A Fading Income

The 100% Guaranteed Annuity (GA) solves for the longevity risk problem. With this type of annuity you exchange your capital for a predictable income stream you cannot outlive. It is an insurance contract with terms agreed upfront that cannot be changed.

Your capital is no longer yours to manage or leave as a legacy but you do get peace of mind that the payments will never stop while you are alive.

Even if you are not worried about leaving a legacy behind there is still a potential issue for you to consider though. Inflation risk.

When you buy this annuity the agreement will stipulate the income you receive and how that will be adjusted year after year. In this example we selected an annuity which increases by 5% per year.

But since inflation is assumed to be 7%, your income will not keep up with your real world expenses. Also known as a loss of purchasing power.

The model reveals that the GA fails to provide 100% of the required income from age 80 onwards. By age 85, it covers only 88% of your needs. At 90, that falls to 80%, and by age 100, your “guaranteed” income covers just 67% of your lifestyle costs.

You won’t run out of money, but you may run out of your income’s ability to cover your living expenses fully.

3. The Hybrid "Blend": A superior system

This brings us to the most powerful finding from the analysis.

When you stop seeing this as an “either/or” choice you can potentially build a better solution to solve for both longevity and purchasing power risk.

The model tested a Blended Annuity where 40% of the initial capital (R4 million) was used to purchase a Guaranteed Annuity, with the remaining R6 million invested in a Living Annuity.

The results speak for themselves.

First, the blend provides 100% of the retiree’s required income all the way to age 95, improving on the  GA’s purchasing power problem and the LA’s longevity problem.

And what about your concerns over leaving a legacy behind?

After 30 years of providing an income, the Blended Annuity’s capital had grown to R17.3 million, more than four times the R4.1 million projected to be remaining in the pure Living Annuity portfolio. (As mentioned you do not get to leave any of the GA capital to beneficiaries).

Conclusion:

This analysis shows that an intelligent, blended approach is potentially a superior solution designed to mitigate the primary risks of both standalone strategies.

That could transform everything for you and make your tough decisions easier at this crucial time.

Lets chat if this is something you want to understand and potentially include in your own retirement planning transition.

By the way……. If you are still feeling a little overwhelmed and perhaps have even more questions as you approach retirement? Why not check out my RETIRE READY workshop designed to help you make the best decisions from a position of real knowledge. Find out more here: RETIRE READY