Key takeaways:

South Africans investment returns are impacted by:

  • What they invest in – Asset allocation (cash/money-market, fixed-income/bonds, equities/shares, & property)
  • What the market does – Asset Allocation
  • What tax they pay on your investment returns – Asset LOCATION or the type of account you hold your investments in. (retirement funds, tax free savings accounts, endowments, taxable accounts).
  • What fees they pay to those that help you choose, administer and manage those investments – Advice, Admin & Investment Management.
  • Inflation or how much your cost of living increases each year. (Consumer Price Index or CPI)

Beware the false promise

I don’t believe misrepresenting returns is a good way to initiate a meaningful relationship – but apparently not everyone agrees with this. 

Investment returns are increasingly headlining in social media marketing campaigns by various advisors and wealth management practices.

You will have seen them. The hook is a nice big number in the lead graphic – If you have not earned at least *15% you need to talk to us, type of thing.

That nice little *asterix is your clue to two things….

Those returns are not guaranteed (and their compliance department should not allow them to insinuate such even if covered in the small print).

It is likely to be based on some really good recent returns which usually means they won’t be repeated. (2025 was an unusually great year for SA assets remember)

REMEMBER: Past performance shows you the returns you are not going to earn.

This makes understanding how returns really work, including what a reasonable return expectation is,  crucial to being able to make good decisions for yourself.

At the simplest level, investment returns are what you receive for letting someone else use your money.

What determines those returns and importantly how much of them you get to KEEP, is a little more complicated. 
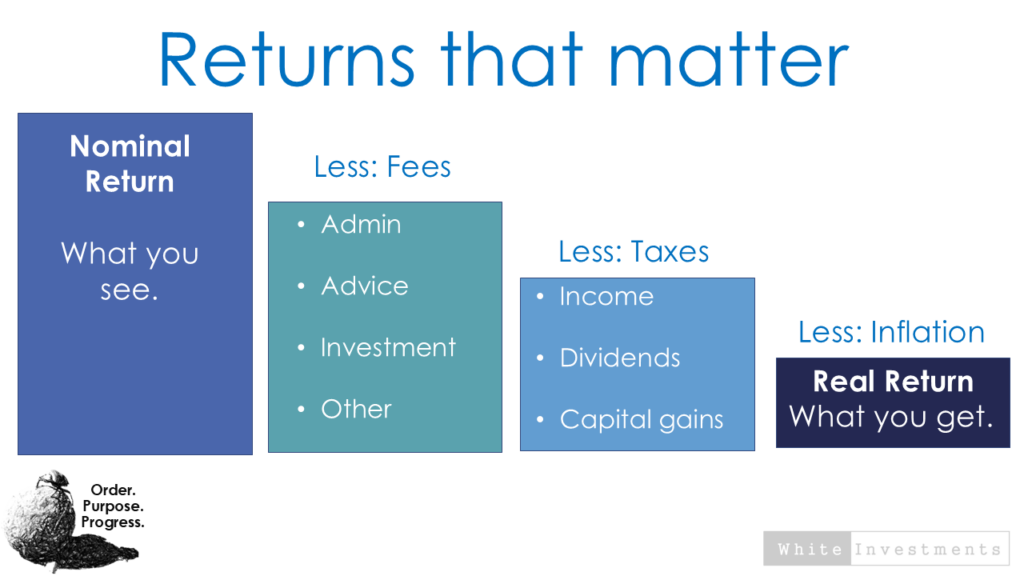
Your headline or nominal return is usually what most people are focused on. (including sales and marketing peeps it seems).

It is linked to your investment strategy (what you invest in – Asset Allocation) and what you get to see in a factsheet for example. 

But the real compounding of your wealth, is one that protects the purchasing power of your money. This needs to account for costs, taxes and inflation.

These are the REAL RETURNS you get to keep.

1. What you invest in:

There are only two broad ways you can earn returns. Income and growth in capital.

A ) Growth Assets:
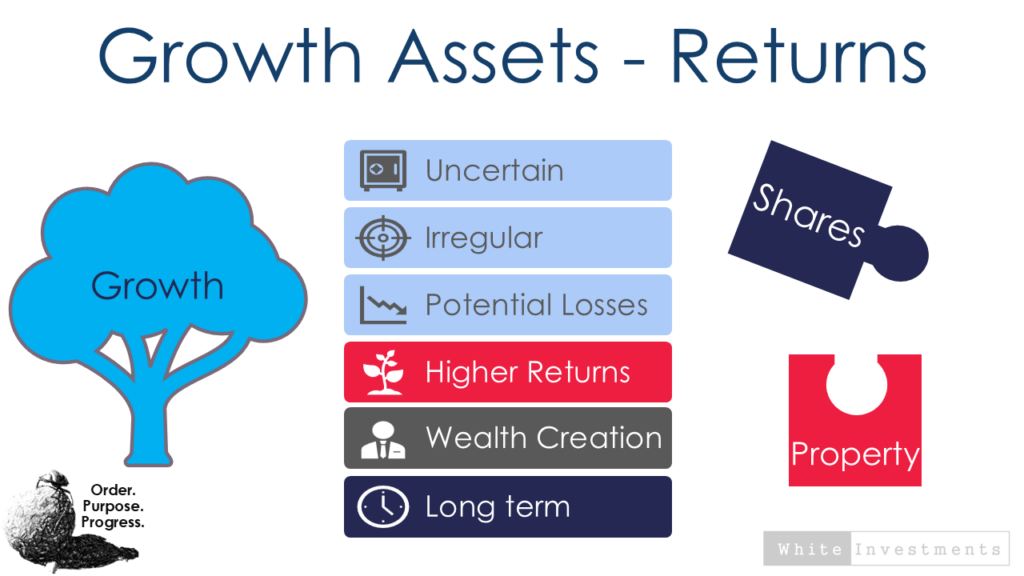
Euity and Property investments earn returns from a combination of income and capital growth (increase in value or price).The income, in the form of rental or dividends, also typically grows over time. But the returns are less certain over short time periods, and so these types of investments are better for long term wealth creation.

B)Income A
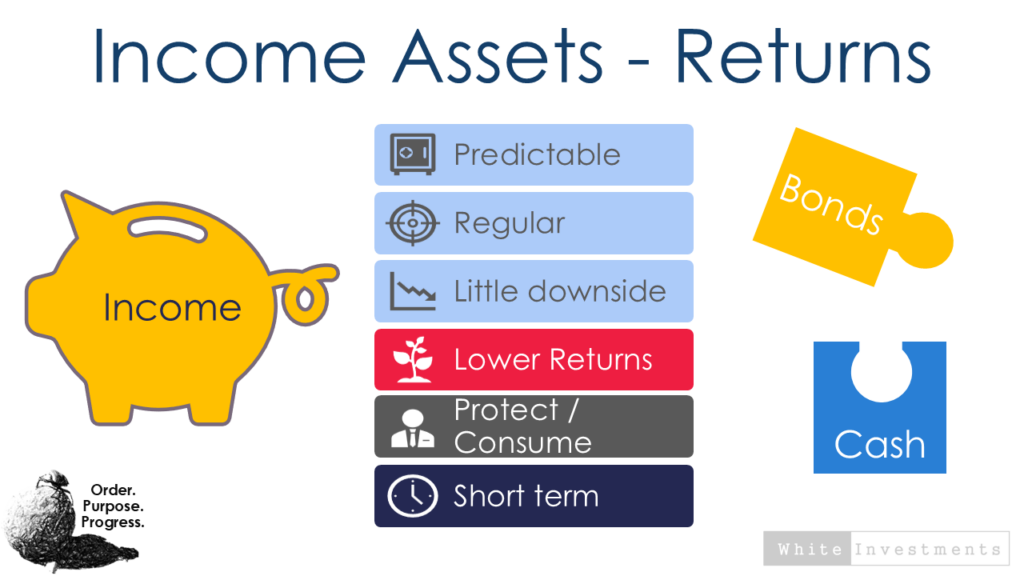
Cash and bonds produce returns predominantly in the form of interest income and these returns are therefore more predictable and certain. This certainty of returns, usually comes at the cost of delivering lower returns over the long-term. This makes income assets great for short-term goals; they can provide predictable cashflows and capital preservation.

How do you choose what to invest in?

Any goal or objective has a future amount of funds needed, an idea of what you can contribute towards the goal and some future date you want to achieve it by.

From these inputs you will be able to get an idea of the investment returns you require to get the job done.

In other words what you invest in is driven by your needs:

  • Your need for certainty (risk).
  • Your need for liquidity (access to your money).
  • Your need for income or cashflows.
  • Your need for returns above inflation (growth).
  • Your need for peace of mind and your ability to stick with a strategy (risk tolerance).
  • It makes sense to align your plan (and required returns) with an investment strategy that gives you those ‘required-returns’ with as much certainty as possible.

2.  What the market does:

Over long periods of time the typical risk-reward dynamics between growth and income assets does hold.  

But over shorter periods they can break down completely.

Most are surprised to hear that South African cash investments beat South African equities almost 44% of the time, if you are watching closely from one month to the next.

But as you extend your time horizon out to 5 year intervals, this falls to just 4% of the time.  
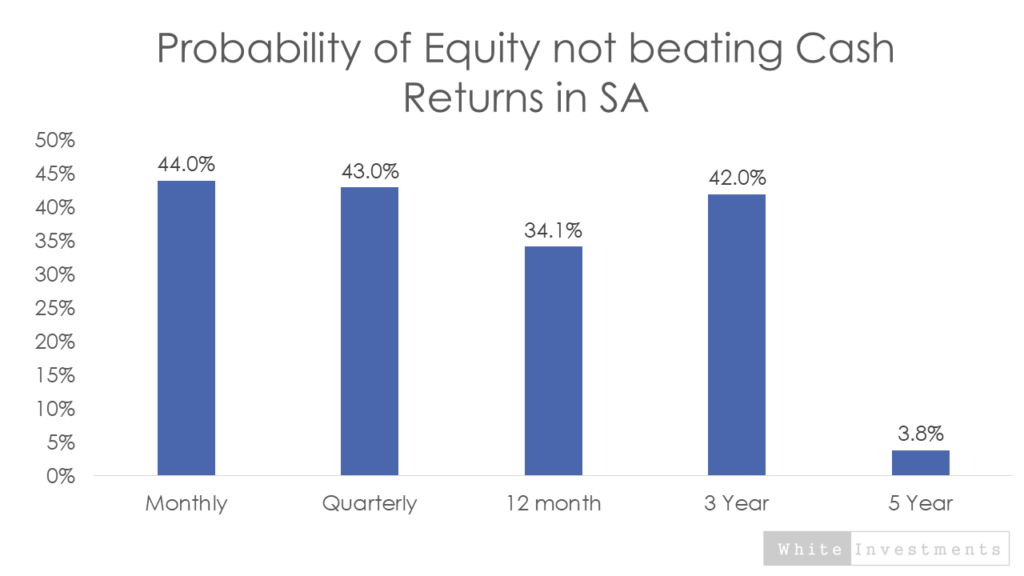
SA equities may have an average return close to 12.8% over the long term (20 years) but will hardly ever actually return 12.5% in any single year.

You will likely receive far more or far less than that average in any given year.
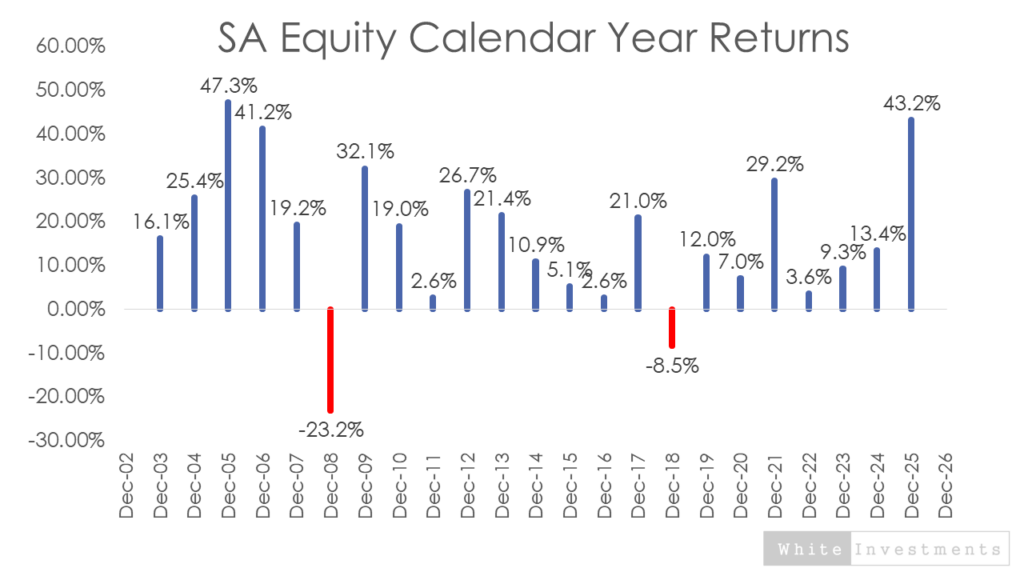
What can you reasonably expect to earn as returns?

It is perfectly reasonable to ask what kind of returns you could expect to earn.
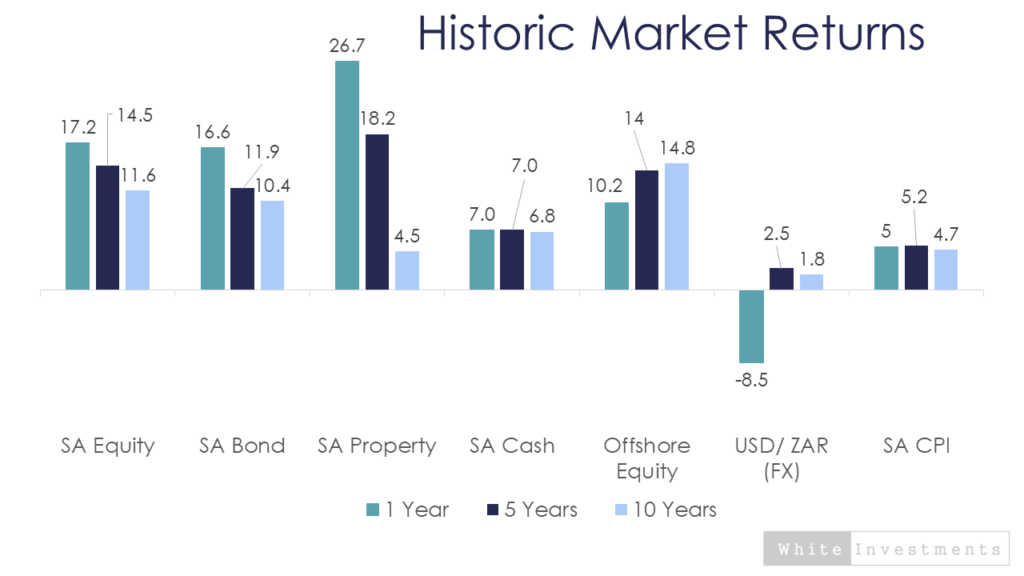
There are many variables that can impact on the investment returns we can reasonably expect to receive over time, so we usually resort to getting a general sense by looking at the historic market returns.
Or alternatively, you can get  a fair indication from products that use a combination of these investments (called ‘multi-asset funds’ or ‘balanced funds’).
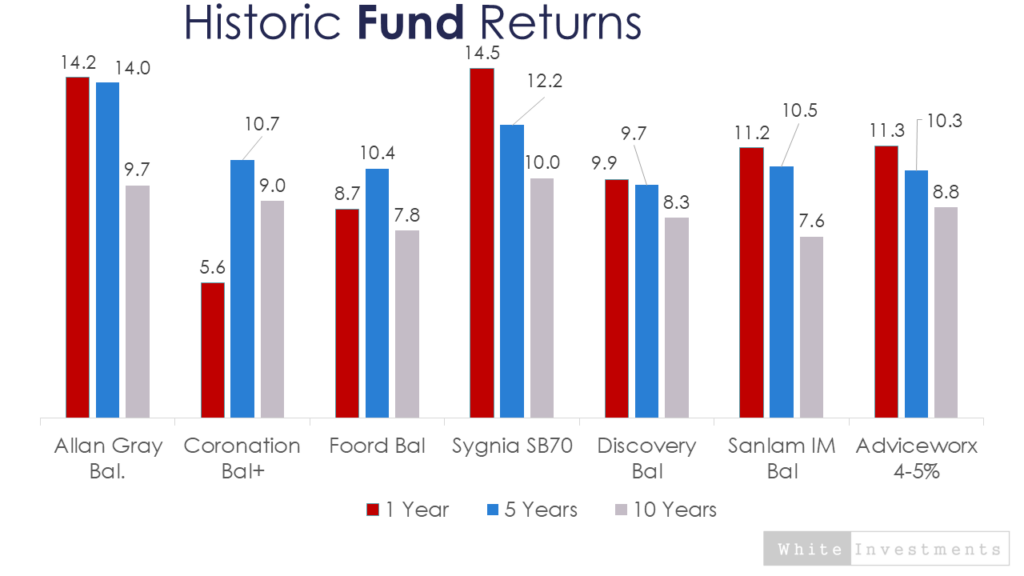
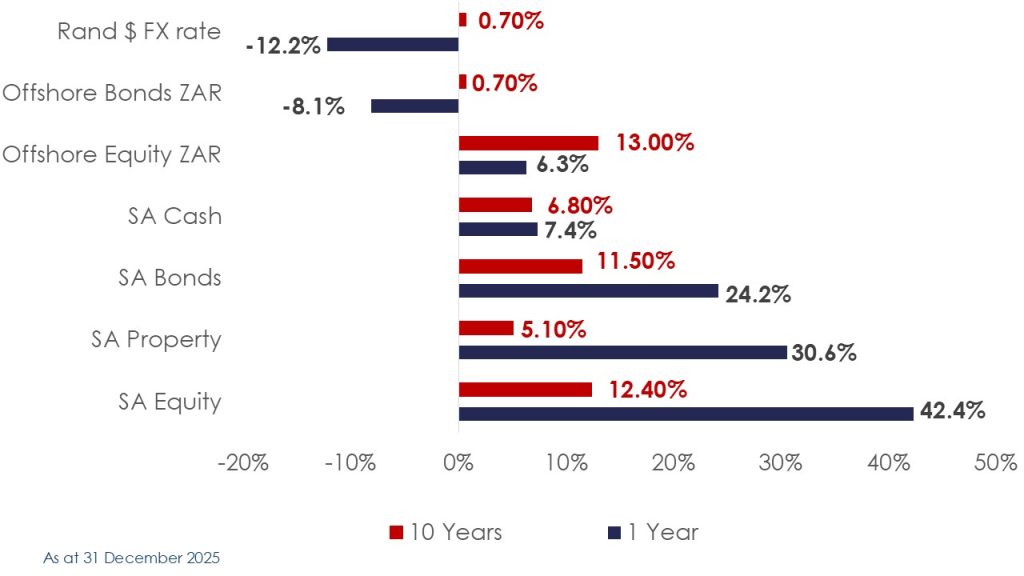
You can see where the sales or marketing messages get the *15% returns from, by looking at the 1-year numbers.  

And you can see why these are probably not reasonable returns to bake into your future plan by considering the 10-year stats.

This basic analysis provides a more realistic measure, as it looks at a longer economic and investment cycle.

A plan based on fictitious return expectations will not get the job done for you and if you are not paying attention, then you may find out too late.

If you do seek help, the promise of lofty headline returns is an easy test to conduct.

A genuine, knowledgeable and experienced partner will have the intention to work with you, in your best interest.

They won’t be trying to hook you in using lofty investment return promises.

3. What tax you pay
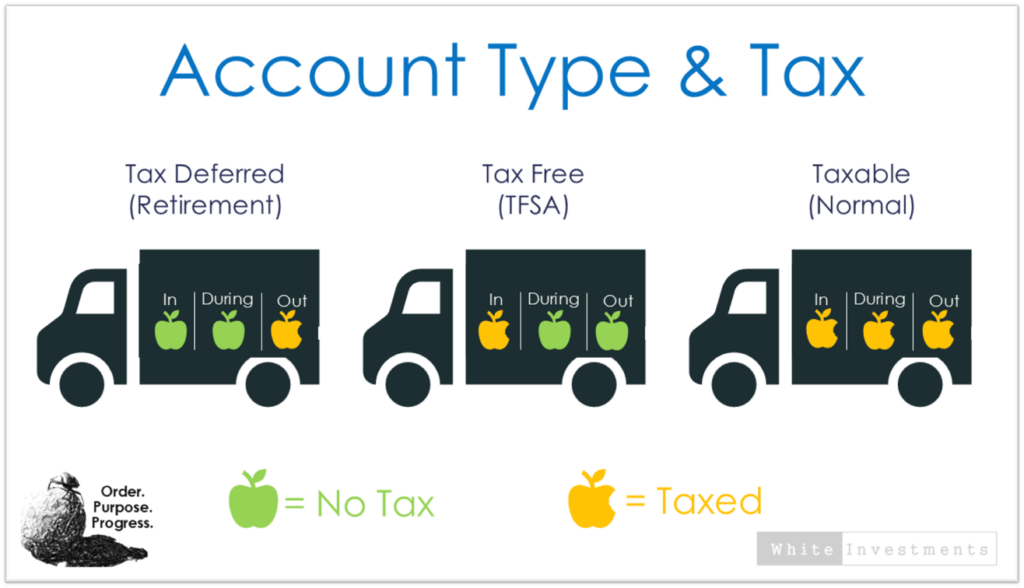
This is the part your real return which you will not see explicitly shown in any statement or report.These ‘returns’ come from saving tax.

Every Rand you save on tax, is a Rand that stays invested, and compounds year after year.

Money paid unnecessarily in tax is a permanent deduction. Once you pay it over to SARS there is no recovery mechanism.

The exact same investments in different types of of accounts will earn different returns.

Tax efficiency in your plan can therefore be just as important as investment choice.

Using retirement funds, interest income allowances, tax free savings and various other tax efficient options is a must.

4. What fees you pay
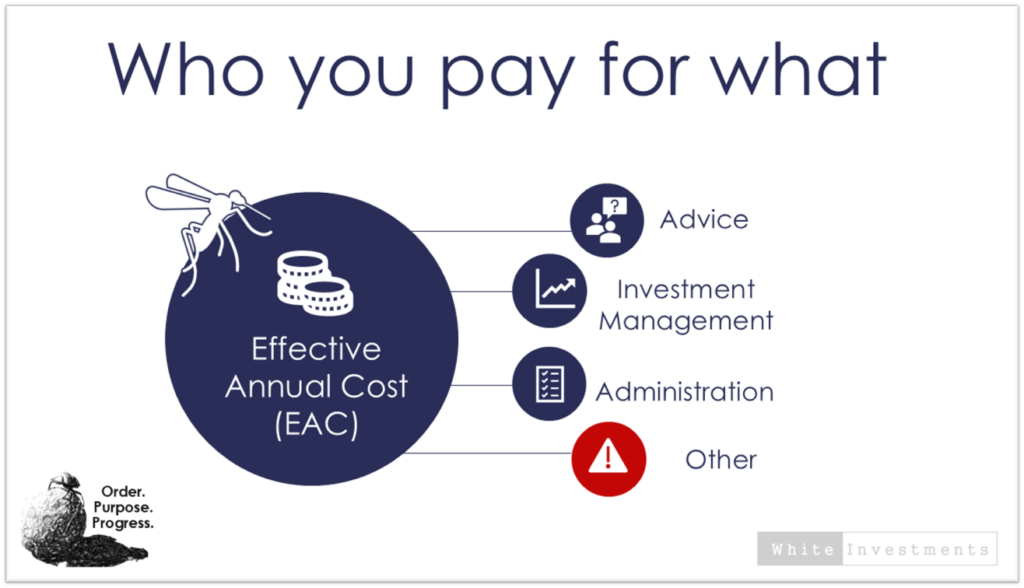
In a similar way as tax, your fees can reduce the returns you keep and compound. So fees are often touted as the enemy to be avoided at all costs.

There is an important difference though.

High fees alone do not mean worse outcomes and neither do low fees ensure a better outcome. Personally,  I don’t think fees are the problem. I am happy to pay fees when I receive something more valuable in return.

The problem comes in when you get no value or the value you get is less than the fee you are paying. 

The solution is to understand what you pay, to whom and for what added value.

You can then determine if you are receiving that value or not.

You get to eliminate those fees or change to a better value proposition.

You have the power and should use it.

PS: Zero fees are not a reasonable starting point as even DIY investors incur fees. You need a platform (admin fee) to manage your money and you need to invest (brokerage/investment management fee for funds or ETF’s)

5. Inflation
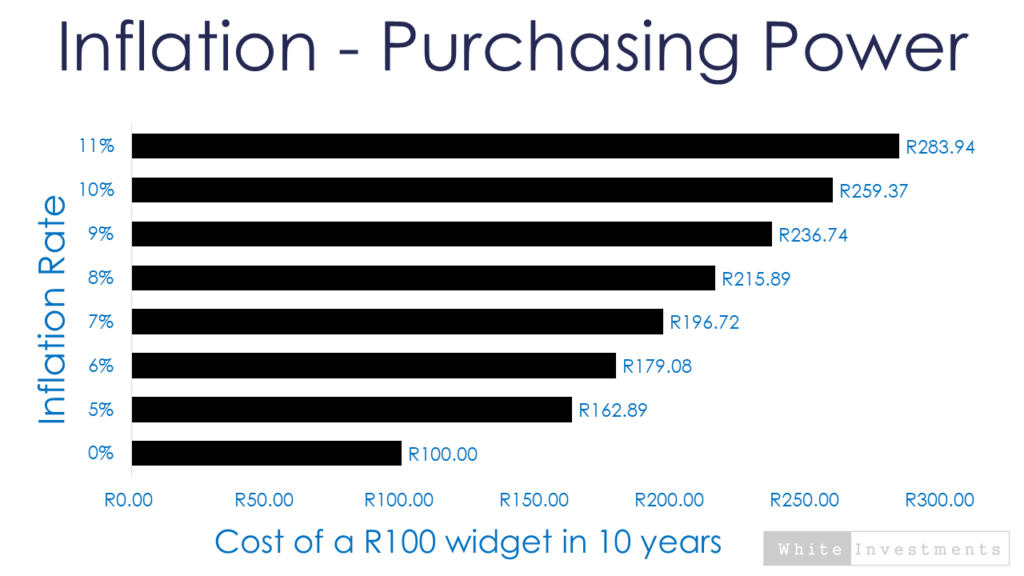
When developing a spending plan for your monthly expenses, or calculating how much you may need in retirement, you need to include some form of increase in your costs each year.

R1000 today and R1000 in 10 years’ time will buy you a completely different amount of groceries when you visit your local store. 

Another way to express this idea is to say that the ‘purchasing power’ of your R1000 has fallen. The same amount of money buys you less this year than it did last year.

The bare minimum return-hurdle therefore, is to make sure you keep up with the increases in your cost of living (inflation).
 
Since each of us consume a different mix of goods and services to make up our monthly expenses, we each technically have our own individual inflation rate.
 
But there is a broad measure of consumer inflation which is calculated and published by Stats SA that gives an indication of inflation  – This is Consumer Price Inflation or CPI for short.
 
You can manage your consumption to some extent, and so from a personal finance perspective, you can manage your inflation.

But a lot of our costs are not in our control, which means we don’t have a choice. Electricity, water, rates and medical fall into this category.

Why this matters to you

Generating the best returns for yourself goes beyond picking the best investments.

Good outcomes are better achieved by being pretty good at personal finances, financial planning and investments combined, rather than perfect in any one.

Everything is linked.

 A system that captures how each element impacts the other and creates the conditions in which you make better decisions at each level is incredibly powerful.

#orderpurposeprogress
Read More

UPDATED AUGUST 2026 –

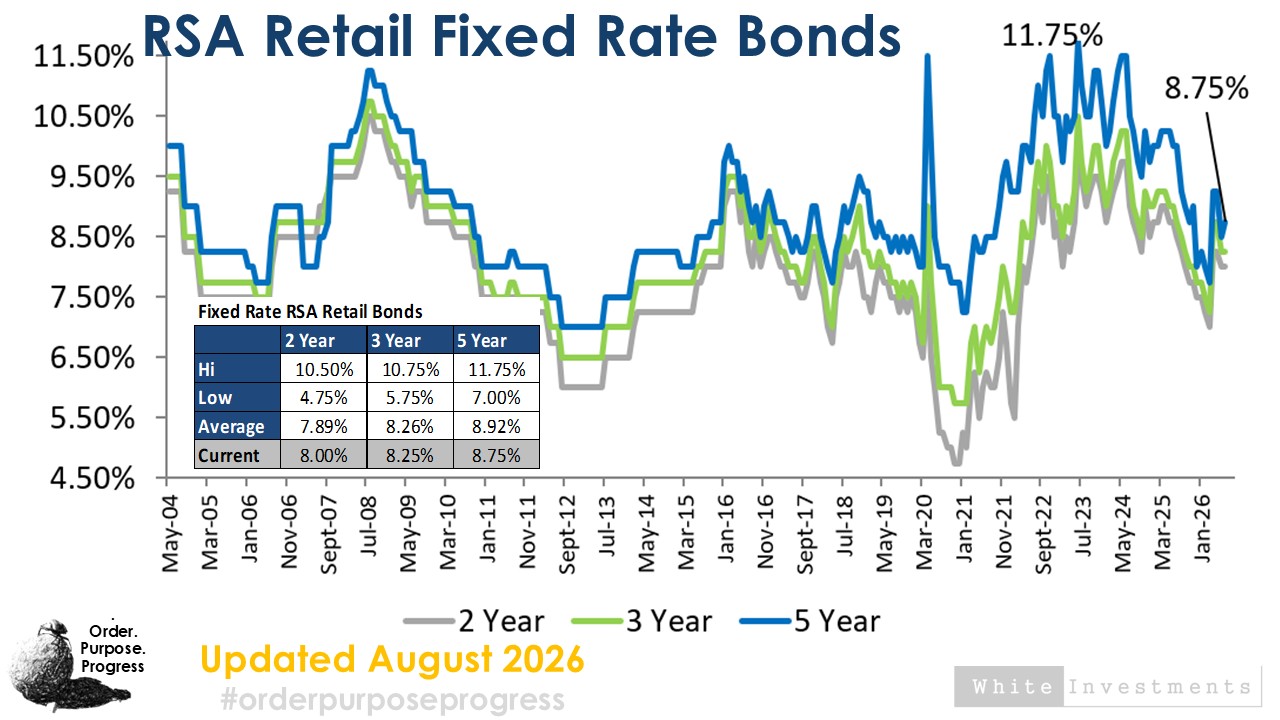
Only the 5-year fixed rate RSA Retail bond yield increased in August. (up 0.25% to 8.75% ).

With the perpetual US-Iran War on-off again, evidence that higher energy prices are filtering into the official inflation data are confirmed.

Of course we have have been feeling that pressure for months already and don’t need the data to tell us things cost more.

But inflation up in South Africa and globally means Central Banks are pushing interest rates higher. (Even though in a surprise move the South African Reserve Banks kept interest rates unchanged this last month).

Bonds are sensitive to changes in expectations for interest rates and inflation.

Yields in most global government bonds are up which is important to monitor as a relative value indicator for South African bonds.

Overall all three fixed rate bonds trade below their long-run averages and it feels like we may see yields higher from here.


The South African government issues RSA Retail bonds.

While I have stolen the idea for the title of this article from an onscreen icon, I will refrain from going into too much of a cheesy metaphor related to the suave, Walther PPK toting, British secret service agent.

Suffice to say that the similarities begin and end with the name – Bond.

https://youtu.be/xDeTocJM1Yo

What are RSA Retail Bonds

In truth there is nothing sexy about RSA Retail Bonds. They are how you can loan the South African government money in return for some, more often than not, very favourable interest rates.

They exhibit none of the “sex and violence”  traits that make for a captivating storyline or sales pitch. They offer none of the adrenalin pumping excitement often associated with stock-picking, where the promise of great riches creates a world of heroes (Apple Inc) and villain’s (African Bank).

It is precisely this boring predictability that makes the RSA retail bond my investment of choice in many circumstances and there are my reasons why I think you could consider them too.

Why invest in RSA Retail bonds

1. They offer better yields than conventional government bonds:

Most of the domestic  bond funds you can invest in will have a majority allocation to South African government bonds (Govvies) of various maturities. The RSA retail bonds (RSA RB) pay a better rate than all of the similar dated conventional bonds and frequently better than most of the longer-dated equivalents too:

Without getting too technical, in “bond speak “ the longer you lend money for, the more you would expect to be paid –  it is riskier to loan money over long periods and longer dated bonds have a greater  sensitivity to changes in interest rates (duration).  Retail bonds show there can be an exception to this rule, from time to time, so we should take advantage of that.

2. They offer better yields than the banks:

RSA Retail Bonds are issued by the South African government and not a bank or other financial institution. In most cases the banks would be expected to pay a higher yield or a premium to lend money from us relative to the government. But the SA Treasury is showing us retail savers a bit of love by offering a better return than most banks equivalent fixed deposit accounts.

3. They are low cost and easy to manage:

The RSA retail bond platform on which you purchase your bonds is absolutely free, gratis, mahala. It does not get cheaper than that and an investment can be set-up and monitored online. There are no hidden annual admin charges. There are no charges for reinvesting the income or making payments from your account. Unlike with the banks there are no requirements to hold other fee paying accounts, keep minimum balances or have minimum contributions. Whether you invest R1,000 or R5,000,000 you receive the same interest  rate as everyone else.

4. The after tax yields are better than savings accounts pre-tax yields:

They are interest income producing assets which means you will be taxed at your marginal rate after you have utilised your annual interest income allowances (R23,800 for individuals under 65 and R34,500 for those older than 65).

But even at a higher marginal tax rate, the after-tax yield on the 5 year retail bond would probably beat the pre-tax yield of about 99% of instant access savings accounts at the bank.

That could be food for thought for those of you holding long-term cash positions in your bank accounts.

5.  Liquidity:

This is often cited as the main drawback of the RSA Retail bonds. These bonds are not tradable on a secondary exchange which means once you have bought them you must hold them for the duration of the agreed term.  After a year you may access your money but you will be penalised, by forfeiting any interest income still owed to you.

This is similar to the offerings from fixed term accounts at the bank. I have no problem with this as it promotes discipline and averts the cheeky dip into savings from time to time.

5. SA Treasury give you a free option:

One of the most unique characteristics of the RSA Retail Bond, and a very compelling one at this stage in the interest rate cycle, is the RESET OPTION. Basically the Treasury is saying invest in a bond at an agreed fixed rate. After 12 months if the rate is higher we will give you the option of switching to that higher rate by re-setting your investment. Most financial institutions would charge you a hefty fee for this option but our friends at the treasury illustrate the willingness to promote savings by giving it to you for free.

6. They can offer the best real yields (Inflation beating):

It is often said that the only sane definition of wealth is maintaining your purchasing power. 

That means making sure that each Rand you save and invest can buy you the same or more each year. 

For that to happen your money must grow faster than the cost of living increases. 

It should be noted here that you can also invest in inflation-linked RSA retail bonds. Unfortunately there is too much to cover in detail in this write up but the choice to go fixed or inflation-linked depends on current pricing, your time horizon and your future inflation expectations.

When should you consider using RSA retail bonds?

I am not advocating RSA retail bonds are the Holy Grail of investment options which will suit all circumstances.

They are not instruments for creating long-term wealth.

If you have a long-term time horizon and no need for income then you should focus on equities and property and other growth related investments which over the long term should provide you with the best real returns.

Matching known future costs or liabilities.

However, if you have a defined goal with a 5-year or less time horizon you can potentially match your future liability with absolute certainty.

Unlike with a share purchase,  the beauty of a bond is that you know right upfront what cash flow (payments) you will receive and when you will be getting them.

If you are already in retirement and looking for regular known payments these may be worthwhile too.

What else do you need to know

These bonds are, as the name implies, only available to individual South African residents. So you cannot buy them in a trust, partnership, as a company, collective investment scheme or as a non-resident. (I believe it is mostly as a result of this restriction that the yields available on these bonds are still so attractive).

Sadly they are not currently available in a Tax Free Savings Account either but I know there are rumblings about changing this.

You can opt to get paid out your interest or you can have it reinvested and compounded over the life of the bond.

You can (and always should) nominate beneficiaries to avoid the executor fees for estate planning purposes. Note they will still be subject to estate duty.

RSA retail bonds are certainly not an investing panacea but they are often over looked relative to other more mainstream (and well marketed) options. If you would like to find out more about RSA Retail bonds you can visit their website or get hold of White Investments who can help you incorporate these instruments into a successful investment strategy.

ballito, ballito investment advice, RSA retail bonds, South African Real Yields, Best income assets in South Africa, best investment advice, Low risk yield, stable known monthly payments for retirees.

Read More

When you die your retirement savings treatment depends on your actions while you are alive.

Retirement funds usually make up a significant portion of an individual’s net-wealth in South Africa.

By naming beneficiaries on your retirement funds, your retirement assets won’t be dealt with within your deceased estate.

This allows you to:

  • Avoid executors fees on these funds
  • Ensure that the funds become available to your beneficiaries faster than if they went through the deceased estate settlement process.

If you have not made beneficiary nominations on your retirement funds as yet, there is a form and 5 minutes worth spending today. Get hold of your service provider. 

What you need to know

In the event of your death, the treatment of your retirement savings depends on whether you were still saving for retirement (pre-retirement), or if you had already retired and those funds are providing you with an income (post-retirement).

If you die before you retire:

  • You will be invested in what are called pre-retirement funds.
  • These include; Retirement Annuities, Pension, Provident and Preservation Funds.
  • You can and should name beneficiaries on these, but your nomination is a guide, not a certainty.
  • Pension Fund Law requires pension fund trustees to pay out the proceeds to your dependents, people that you support financially. These may be different from those you nominate as beneficiaries on your retirement funds.
  • The Board of Trustees of your retirement fund have 12 months to investigate and make certain of who all your dependents are before paying out.
  • They will decide how to split the proceeds based on their assessment of all dependents needs.

If you die after you have officially retired:

  • You will be invested in post-retirement funds which are either a Living Annuity, a Life/Guaranteed Annuity or some combination of the two.
  • You can and should nominate beneficiaries on your Living Annuity funds.
  • Your Life Annuity is a contract which unless you signed up for a Joint-Life annuity (includes your spouse) or have a guarantee period, your annuity will die with you and there is no beneficiary.
  • Your nomination on your Living Annuity is binding and there is no legal requirement for Trustees to determine whether there are other dependents.  
  • The Trustees will pay to the named beneficiaries in the proportion you determined on your nomination form.
  • This means the payout process should be relatively quick.

What your beneficiaries choose to do is key

Your nominated beneficiaries will receive a formal letter to alert them when the time comes that they are set to receive a payout.

It will likely include only a basic outline of the options they have:

  1. Cash Lump-sum: They can receive the money as a cash lump-sum payment. This is taxable as per the retirement lump-sum withdrawal tax tables published by SARS.
  2. Buy an Annuity: They can use the funds to buy an annuity income stream in their own name. There are two types of annuity income they can purchase; a Living Annuity or a Life/Guaranteed Annuity.

The lump-sum transfer is tax-free if your dependent goes for the annuity option, but the future income streams will be taxed as per their individual income tax tables.

It is possible for them to take a portion as a cash lump-sum and use the rest to buy an annuity.

How you can help your beneficiaries

Your beneficiaries will likely receive very little, if any, detailed insight into what the implications and consequences of their choices are.

Yet each beneficiary will have to make the decision for themselves – You cannot control or elect what they do with the proceeds.

So it falls upon you to make this process more beneficial for them. You can arm them with the knowledge to understand the consequences of their decisions and I would like to help you do that. 

I have created a free guide for you to send on to your beneficiaries to help in this process should the need arise.


FREE GUIDE: The Real consequences of your Retirement Death Benefit decisions.

Valuable insights into the process, their options and examples of how your beneficiary’s decisions play out over time. Don’t waste this great opportunity.  

If you would like to receive this guide, please send me an Email: info@whiteinvestments.co.za with the Subject line: Retirement Beneficiary Guide Request

You can only influence what is in your control

Sharing the guide with your nominated beneficiaries is a good start.

On top of that, make sure you have a file which contains the information available for your beneficiaries to share with the Board of Trustees of your pre-retirement funds.

By providing proof of dependency via a marriage certificate, divorce maintenance order, children’s birth certificates and bank statements, you can help them progress their compulsory investigation as quickly as possible.

It will help to avoid unnecessary delays in your beneficiary payouts.

Read More

Key Takeaways:

  • Slow down and don’t make rushed decisions.
  • Remind yourself of the time horizon that is important to you. 
  • Have you got a solid plan in place to start with. Revisit it.
  •  Don’t check your portfolio daily of you can help it. 
  • Talk to someone you trust about your concerns. 
There is no hiding from it, the current news flow is alarming.

It amplifies uncertainty which investors dislike and thus leads to market weakness as participants react and re-position.

In truth there has never been a period in history where you could not identify a risk which has the potential to cause a sudden sharp market sell-off. 

Uncertainty about the future always exists. It is just that we perceive it to be higher when it is flashed across our screens constantly or surprises us.

By definition events which upset markets must be a surprise otherwise they are already priced in. The Iran attack (or its extent) was a surprise and what we are seeing is concerning at various levels.

It is impossible to know what the potential downside is with any certainty. Too much depends on  the outcomes and how long it will take to end.

Energy prices are a very big determinant of economic well-being for governments, businesses and us as individuals. It is clear higher energy prices will already have a negative impact.

Too much here is not knowable. 

Checking your portfolio?

If you do happen to check your portfolio you will no doubt see it is off its recent highs.

Even with a well-diversified portfolio you may be back to where you were in December of last year.

I would encourage you not to be alarmed. Which I admit is about as useful as telling someone to calm down in the middle of a heated argument.

There is a strong argument to be made for not checking your investments regularly, especially at times of heightened uncertainty.

We all suffer from loss aversion and have a deep desire to act to avoid further losses. The urge is powerful and emotions can often trump logic.

But a market downturn is not the right time to be reassessing your tolerance for risk.

You will have less appetite for risk when markets are down 20% in real time, relative to how you felt considering the potential for a 20% paper-loss when markets were looking solid. You are human.

Here is a little experiment


Which one of the following investments would you pick?
You probably chose C right. I know I did.

Because all three assets finished at the same value, but C did not experience any downside.

It’s what we all want – All of the upside and none of the downside right.

But it is a trick-question.

All three assets are in fact the same Global Stock Index during the calendar year 2020. The good old pandemic year.

The difference?
A = checking your portfolio daily.
B = checking your portfolio monthly.
C = checking your portfolio once a year.

Good message but too neat?

I think it is a great message – worrying about short-term performance is likely to encourage bad behaviour.

But I also think it is unrealistic a lot of the time.

The 2020 market sell-off and then recovery was one of the fastest in history. So much so that it quite literally felt like it never happened. A few trillion dollars turns out to be an effective band-aid for a global shutdown. At least for asset prices.

The Global Financial crisis of 2007/2008 was very different. It took over two 2 years for the recovery to happen. That is a long time spent watching things deteriorate, even if you only look at your portfolio once a year.

If you were close to retirement,  or indeed already retired in 2007, seeing markets almost halve would have been traumatic.

Approaching an end goal requires more hands-on management leading up to the actual event – Simply not looking at your portfolio is unlikely to be very helpful.

There is risk in selling too

A truth you learn through experience is that selling out of risk assets is often the easy part.

After a period of strong market performance most people are enjoying great gains. Locking in some of that feels good.

And it could be sensible in so far as it fits with your strategy. In other words some kind of portfolio rebalancing.

But to sell risk assets (below your strategic allocation) to protect yourself from further downside near term, means you must decide when to buy back into markets too.

And this is far trickier than you may think.

When the market bottoms, no one waves a flag to give you the all clear signal. Putting money back to work in a down market feels like you are exposing your portfolio to even more losses. So many people wait.

The market bounces back by 10%. They agree that on the next pull-back they will buy. The market never has that pull back and the investor remains out the market and does not enjoy the returns that follow.
 

Focus on the goal

If you are a client and are receiving this then you have a solid, well considered plan.

That plan will have incorporated  your goals, which means we know your time horizon, your required returns and any cashflows into or out of your investment portfolios.

Your asset allocation will have already considered the potential for a sell-off, as these things happen to some extent more or less each year. And about every five years markets can experience what feels like catastrophic losses. What you are currently invested in will have considered your goals ability to withstand such scenarios.

If you have big cashflows INTO your portfolio we will have considered this too. Inflows we can largely ignore into weakness because buying into a weaker market is beneficial to you.  

It is the cash OUTFLOWS which are more of a concern because if you have not made provision for them in your plan then you risk needing to sell assets which have fallen in value to meet these cashflows.

If you and I are investing together I will have factored these cashflows into your plan for you. You will not be in a position where you are forced to sell assets and lock in losses.

Talk it over

Headlines and market commentators will frequently use fear as a marketing tactic at times like this. They intend to cause you doubt and possibly even scare you into action.

Do not be hasty. You would do well to take some time to seriously consider any potential action. 

If you are not sleeping well at night, then you may want to revisit the goals you have set and the investment strategy you have in place.

If all is in order, I hope that will help put things into perspective and provide some peace of mind.

I am here if you would like to discuss anything about your plan or portfolio that we have worked together on.

If we have not worked together as yet and you are feeling a little anxious, lets have a conversation and see where you are at if you like?
 
Read More

Inflation impacts almost every financial decision you make.
 It would have been easy to miss or dismiss the South African Reserve Bank (SARB) and Treasury officially declaring their intention to target a lower inflation rate late last year. 

In my opinion this was the biggest news event from 2025 in terms of potentially having the largest ongoing impact on your finances.  
 

Why it would make sense:
1. A lower inflation rate would likely lead to lower bond yields longer term. Bond yields represent the interest rate that the SA government pays on its outstanding debt. A lower borrowing cost, would mean the government spends less of it’s annual budget on servicing its debt. 

2. A lower inflation rate should feed through to lower expectations for the governments very high public wage bill and could therefore also help cut spending. 

3. Lower inflation would lead to lower interest rates over time. Lower interest rates would mean cheaper money for investment and growth and lead to better economic conditions, higher corporate profits, possibly lower unemployment, which if extrapolated far out enough, could lower crime rates etc etc

A Virtuous Circle that makes SA more attractive and investible and should impact positively on all citizens lives.  

Why it won’t be easy to achieve:

Many costs that make up your monthly expenditure are not driven by market forces.

1. Some prices are administered (set by a regulator), like water and electricity.

2. Some prices are raised above CPI rates, like education, healthcare and medical aid premiums. You tend to have less power to reduce spending in these departments and often have to accept whatever is charged. 

3. Other prices, fuel for example,  are driven by external factors like the oil price, and the exchange rate. These factors are often sentiment driven and out of your control. Added to which, about 33% of the price you pay at the pumps is actually tax and levies. Fuel prices feed through into food and other goods via transport costs and so are far more impactful on inflation than merely the price paid at the pump. 

These factors mean CPI is not a good measure of your personal inflation rate. Monitoring your own spending plan will give you a much better idea of your personal inflation rate as your consumption basket is unique to you, your lifestyle and your life-stage. 

Inflation has important implications for the three main areas you need to be on top of in term of successfully managing your finances.

#orderpurposeprogress

CREATE ORDER : Impact on your personal finances


Your personal income statement:

This is how you track what you have coming in versus what you have going out, identify disposable income for future contributions and understand what you need to protect from a risk planning perspective. 

If inflation settles at 3%, salaries and wages will likely grow more slowly in future.

Markets can and have already moved to price in expectations around this new inflation target. Bond yields are lower and further interest rate cuts are expected. You will have to factor in lower investment income from your savings. 

But your expenses probably don’t feel like they have adjusted downward as yet. That will take time if it happens at all. 

That mismatch can create short-term cash flow pressure which you will need to manage and potentially plan for going forward. 


Your personal balance sheet:

This is how you measure and monitor your net wealth, your progress towards specific goals, your tax planning and estate planning positions. 

A lower interest rate environment would be good for people with high levels of debt on their balance sheet but not great for savers or those that rely on their investment income to live off. 

The existing assets on your balance sheet, be it an investment portfolio, your retirement funds or your home, grow as a result of either receiving an income (dividends, interest, rental) or from prices going up.

A lower inflation rate could potentially lead to a lower nominal growth in your assets and therefore your personal  balance sheet over time.

Inflation expectations are baked into expected investment returns.


HAVE PURPOSE: Impact on your financial planning

The rate at which you adjust the cost of whatever you are planning for in the future (inflation) is one of the key assumptions in the financial planning process.

All your stated capital goals (education costs, holidays, holiday homes, vehicle purchases), your income requirements (pre-retirement planning ) and cashflow planning (post-retirement planning) use inflation to get a reasonable expectation of what will be needed to ensure a successful outcome. 

Most of the plans I put together currently use an annual inflation increase assumption of between 5% and 7%.

Adjusting only your inflation assumption to a lower level will reduce all future costs and essentially make your goals look far more achievable.

For example:
If something costs R1,000 today and you need to replace it it in 20 years:
At 3% inflation, the replacement cost would be R1,806
At 6% inflation, the replacement cost would be R3,207

If we keep all other assumptions the same, starting from zero today your required contributions would be:
At 3% inflation your required monthly contribution ≈ R2.10
At 6% inflation your required monthly contribution ≈ R3.75

It may be tempting to update your plan for a 3% inflation rate immediately but that would almost certainly make your planning process far less robust. 

The reason for this is that if we reduce our expectations for future inflation, we should reduce our expected returns from our portfolios too. 

In fact, in the financial planning process, the returns you use must account for more than just inflation. They account for costs and taxes too.

These are called your real returns and are far more important to your success than the nominal returns you would see when comparing asset class returns or even fund factsheets. 


MAKE PROGRESS: Impact on your investment strategy and management

In simple terms investing is about earning returns to meet some future use or objective. 

Rational investors allocate their money to investments they believe will deliver the returns required to get them to their goals with as much certainty as possible. They want to get a job done.

That job could be about creating wealth (increasing the purchasing power of your money) or maybe it is about wealth preservation (maintaining your purchasing power over time).

For the majority of investments, the returns generated are a function of what investors are willing to pay for the future cashflows those investments will deliver – Earnings for shares and interest income for bonds. (Gold and Crypto do not produce any cashflow and rely on prices continuing to go up to generate a return). 

Investment choice is also impacted by the risk investors are able and willing to accept to take in order to earn returns.  

If you are trying to grow your wealth or even just preserve it, it is logical that your investment strategy would not invest long-term in things that fail to produce real returns (protect your purchasing power). 

Income assets which deliver more certain returns will  track interest rates and inflation lower. Probably reducing the real returns you receive.

Growth assets could get a boost from a more stable inflation environment through various mechanisms like better economic growth, higher profit margins and  lower debt servicing costs all feeding down to the bottom line. The real returns you receive could therefore be more stable or even grow over time. 

Your investment strategy will need to balance income requirements and preservation against achieving the required growth to maintain your purchasing power.

There is a good chance that you will need to  incorporate more growth assets in order to meet your return requirements. These growth assets will in turn increase the potential  for losses over short time periods. 

For those consuming their wealth, this shift will increase the sequence risk (The order in which you earn your returns in the consumption phase of your journey) in your strategy. If you are forced to sell assets to cover your consumption needs when market prices are lower, you will lock in permanent losses. 

Sequence risk is usually mitigated by owning safer income assets to match at least a few years of required income. Lower returns from these income assets would make this more of a challenge. 

What I am contemplating:


  • Life Annuity rates offered by insurers are linked to long dated bond yields. They are already significantly lower as a result. A lower inflation rate could impact them further including the amount by which they contractually increase annually (escalating annuity). 
  • From a Living Annuity perspective, lower returns without lower consumption will increase the drawdown rate and stress the longevity capacity of the portfolio. 
  • If safer income assets are not delivering real returns but required returns stay high, this could put pressure on the need to take on more investment risk to achieve the required long-term returns. The need for a more dynamic and proactive approach to asset allocation is probably required for those in the consumption phase of their wealth journey.
  • South African’s have for a long time relied on the Rand to devalue against developed market currencies like the US Dollar, Sterling and the Euro, to enhance returns from offshore investments. While sentiment drives FX rates short term, it is the difference between the two countries inflation rates that drive the long-term relationship. If SA and US inflation are much closer in future, it would make sense not to expect the same level of devaluation of the Rand going forward. 
  • In a lower nominal return environment, the impact of fees will also become more noticeable. 2% on a 15% return is very different to 2% on an 8% return. Sharpen those pencils. 
  • Tax planning and making use of the tax mitigation options available to individuals will become even more important (see the Good News below). A high growth balanced fund incurs about 1%-1.25% per year in tax liability when invested outside of retirement fund or tax free savings account. With a focus on real returns this will be a tool that needs to be well utilized. 
Read More

Should you invest in an endowment policy to save tax as is so often recommended?

The answer lies in understanding the difference between your MARGINAL and EFFECTIVE tax rates. 

The type of account you hold your investments in determines how you are taxed. Endowments are taxable accounts. 

Tax is taxing at the best of times.

The one thing we can all agree on is that we would like to pay less of it.

Many people are advised to invest in an endowment policy when their MARGINAL RATE of tax is above 30%.

This is because your investments in an endowment policy are essentially still the life company’s and so you are taxed at the flat rate of 30% on all income. 

What is your marginal tax rate?

Your MARGINAL RATE of tax is easy to determine. Just consult the Individual Income Tax Tables that SARS publishes annually (see graphic below), see where your income fits into the scale of income bands. That % number under ‘Rates of Tax’ is your marginal rate of tax.

‘Marginal’ meaning each additional Rand of income is taxed by that percentage.

SARS individual income tax bands for 2025.

What is your effective tax rate?

The taxman allows certain deductions which impact on the income tax you pay each year.

Some of the more common ones that are applicable to most individuals include: 

– Individual rebates. These increase with age. Under 65. 65>75. Older than 75
– Medical tax credits which include payments for medical aid premiums and other medical costs.
– Interest income allowance.
– Capital Gains Tax allowance.

The table below illustrates how deductions can change a persons effective tax rate. This is  how the exact same income, for 3 individuals of different ages, would be taxed in practice.

Same income, different income tax.

You will note that each individual has the same marginal tax rate, but the older you get the more deductions you are allowed. This reduces the amount of income tax you pay.

The amount of tax you actually pay as a proportion of your income is called your EFFECTIVE TAX RATE.

At lower income levels, the EFFECTIVE RATE of tax is significantly lower than the MARGINAL RATE. 

In fact the tax paid by someone who is 75 years old is R2,655 per month less than a 64 year old. That’s almost R32,000 per year. (2025 Tax tables)

This would not be the case if your money was invested in an endowment.

How much income would it take to get to an effective tax rate of 30% in your personal capacity?

About R1,350,000 of income. This is a marginal rate of 41% by the way. 

Anything below that number would mean you pay more income tax in an endowment structure than if you held the investments in your personal capacity.

Estate planning

For completeness, an endowment can be useful as an estate planning tool, and I am not implying you should never own one. But that is a potential topic for another time. 

Just be sure if you do own an endowment, it is doing the job you intended it to do!

*Assumptions in the tax calculations: An income of R514,500 plus interest income of R40,000 per year. Medical aid premiums of R8,800 per month with R2,000 in additional medical expenses. 

Reach out if you have any questions on the above or if you would like help making progress in your financial life.

Email Dominic

Follow White Investments Facebook Page for insights, motivation and sometimes a bit of fun.

This article first appeared in White Investments monthly newsletter. Sign up at the bottom of this page or check out past editions here.

Read More

You know how I bang on about getting value for the fees you pay? 

Because fees reduce what you get to keep an compound over time?

Well tax is similar.

If you are paying more tax than you need to, then you are reducing what you get to keep and compound over time too.

Best you sharpen up your mindset and your pencils as soon as you can.

SARS gives you many ways of reducing the amount of tax you pay, either now or in the future.

Some quick wins:

  • Split income – If your spouse is in a lower tax bracket, shifting income-producing assets can reduce your overall tax burden.
  • Maximize deductions – Retirement contributions, medical aid credits, and even certain expenses related to earning income can all work in your favor.
  • Use tax-free investments – If you haven’t maxed out your annual tax-free savings allowance, now’s the time.
  • Use retirement funds – Don’t listen to the naysayers. These things are one of your best tools to grow your wealth quickly.

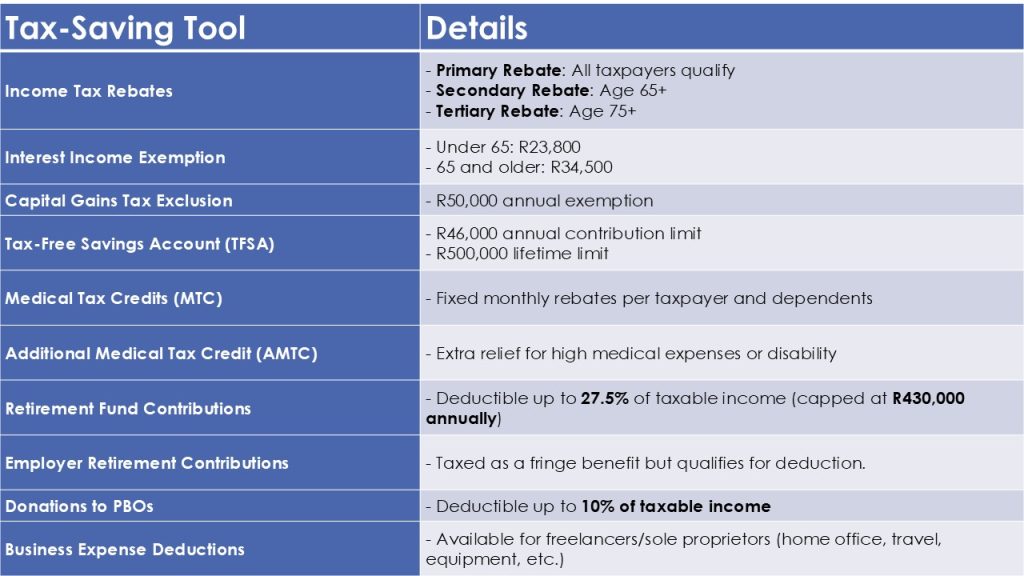
Here is a list of tax reduction tools can make sure you are using as effectively as possible. 

Reach out if you have any questions on the above or need help making good progress in your financial life.

Email Dominic

Follow White Investments Facebook Page for insights, motivation and sometimes a bit of fun.

This article first appeared in White Investments monthly newsletter. Sign up at the bottom of this page or check out past editions here.

Read More

2025 was a great example of why, as a South African, you should never have 100% of your investments offshore.

It was a sensational year for local assets, while the double digit appreciation of the Rand (ZAR) versus the US Dollar (USD) reduced returns from locally held offshore investments.

You may remember

If you were one of those South African’s reading Magnus Heystek’s sell everything, pay the tax and go 100% offshore a few years ago, this would be a good opportunity to recognise the value in a more balanced approach.

When you live in SA and the majority of your costs (liabilities) are in SA, you cannot afford to have all your money offshore for this exact reason. 

I would go one step further. Mentally store this information for the next time someone urges you to go 100% offshore. (there will be a next time)

Even just one year ago it was easier to believe the Rand would trade at 25 to the US Dollar than to think 15 was possible……  how things change.

The past returns of an asset are the returns
you are not going to enjoy.

A comparison between the 1 year returns and the average return over the last 10 years, can provide some insight.


The real question remains what comes next?


Asset Class Returns – 1 & 10 Years to end December 2025

Looking at average returns over longer time periods suggest that returns over the next few years will probably not match 2025.

This is not the same as saying 2026 will see a major sell-off. 

Fact is:

– Strong recent performance makes assets more expensive.
– Future returns are determined by the price you pay for the assets you own.
– Ergo periods of sustained strong performance are likely to be followed by more tepid returns.


You know what helps

Managing your expectations around returns and accepting that occasional sell-offs or downturns are what inevitably bring us closer to long-term average returns over time is important. 

Sell-off’s are a feature of investing, not a bug that can be fixed or avoided altogether. 

Matching your investment strategy to what you are trying to achieve, knowing you can’t predict future returns is why you build a diversified portfolio.

100% Offshore is never the right option if you are looking at your overall financial position.

Read More

It is often a good starting point to accept that things won’t always go to plan.

My family’s happy place is in nature. We enjoy our birding and our two young sons are quickly developing the skill-set, knowledge and enthusiasm to outpace our own abilities. 

I have also always enjoyed photography. One of my toughest subjects to get right has been the oxpecker.

I have taken thousands of pictures of this bird, on all varieties of animals, and never once achieved the shot I wanted.

Composure, focus or light was always lacking. 

Earlier this year, we entered the Hluluwe Imfolozi Park and within 100 meters, we stopped at a puddle in the road.

The oxpecker washing itself came and sat on the bonnet of our car.

The picture above was taken through the windscreen.

Yes, through the windscreen. Not a photographers dream. But the end result is probably the best shot I have ever taken of an oxpecker.

It was all luck. Sure we had to be in the right place. But we could not possibly have planned for this.

And the outcome was better than anything I had achieved previously.

A timely reminder that there are so many things we cannot plan for perfectly.

Things often take longer than we think and rarely work out exactly as we expect.

But as long as the outcome is what we were aiming for, in the time frame we were aiming for, then we should be okay with that. 

It is the outcome that matters right?

I read somewhere the other day  – The best risk management process is financial literacy. 

The idea being, if you can understand how money & markets work, you can set up your finances, plan and investment strategy to capture outcomes that get you to your goals.

You will also manage your expectations around the very wide set of potential outcomes your plan and investment strategy will need to endure.

Ultimately, you will find that you can better weather the inevitable surprises, disappointments and deviations.

And that should make the journey more pleasant and probably even successful. 

#orderpurposeprogress
If you have any questions about the above or would like to see of we are a fit and how I can help support you in managing your financial life please get hold of me:

Email Dominic

Follow White Investments Facebook Page for insights, motivation and sometimes a bit of fun.

This article first appeared in White Investments monthly newsletter. Sign up at the bottom of this page or check out past editions here.

Read More

Key Take Aways:

  • Choosing how to structure your annuity income is a critical decision.
  • It is not an either or decision between a Life and Living Annuity.
  • You can blend or use a combination of annuities.
  • It would benefit you to understand your annuity options and the implications of your choices.
  • This case study gives you a feel for how it can work for you.

Deciding how to structure and access the best income from your retirement nest egg? 

This analysis on blending annuity incomes is for you.

A Surprising Revelation

For anyone approaching retirement, one question tends to dominate: “Will my money last as long as I do?”

Traditionally your two main options of accessing a regular income in retirement are:

Living Annuity – Offers flexibility and control of your income but carries a higher risk of outliving your savings if you are not careful. You get to leave any remaining capital behind for beneficiaries.

Life (Guaranteed) Annuity – Provides income certainty as the income is guaranteed to be paid for the reminder of your life. The catch is that any unused capital cannot be left for your beneficiaries.

This can turn the decision making into a tug-of-war in your mind: the desire for flexibility and control versus the desire for certainty and a good night’s sleep.

But it does not have to be one over the other.

If you make the decision before retiring from your funds, you can make use of a combination of the two.

You may be pleasantly surprised by the findings.

The Analysis

If we analyze and compare these 3 options using a financial model, we can see exactly where the risks lie and how they can potentially be mitigated.

In the following case study we consider the 3 options:

(1) A 100% Living Annuity (LA)

(2) A 100% Guaranteed or Life Annuity (GA)

(3) A Blend of the two – 40% GA and 60% LA

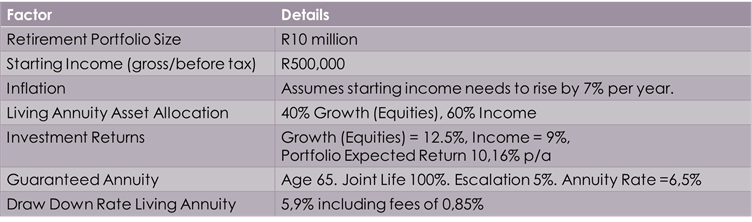
Firstly, as with all models there are some key Assumptions that need to be made. Here is a summary of them:

Assumptions for the blended annuity analysis by White Investments.

Comparison tables of the key findings:

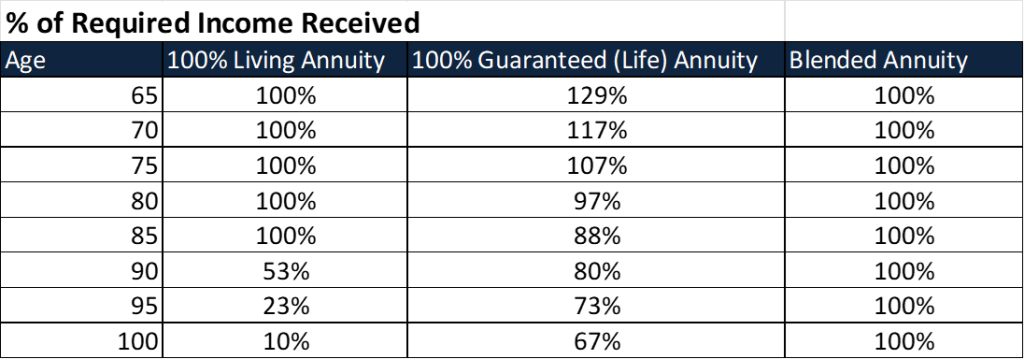
Percentage of required income received

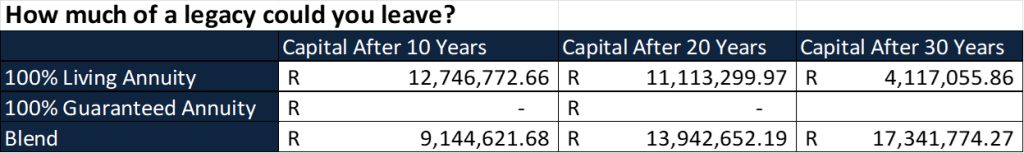
What about how much you can leave behind for beneficiaries

Please note the legacy values expressed above do not take into account inflation (nominal values). The real feel, or purchasing power, of the 20-year capital value,  if inflation was 7%, would be R2.8 million for the 100% LA and R3.6 million for the Blended option.

1. The Flexible Living Annuity can be a longevity trap

The 100% Living Annuity (LA) is attractive because it puts you in control. Your capital remains invested, giving you the potential for inflation-beating growth and the flexibility to adjust your income. However, this control comes with longevity risk, the danger of your money running out before you do.

In a high-inflation environment (modelled here at 7%), this risk is significant. The model shows the pure LA is projected to fully meet your expected income needs for 21 years.

For the first two decades, everything feels fine. After age 85 you reach your maximum LA cap of 17.5% of your portfolio, and your income falls quickly thereafter. By age 90, you are projected to cover only 53% of your income needs.

This is where the initial comfort of a flexible annuity can feel more like a trap, and there is little that can be done about it by that stage.

2. The Guaranteed Annuity’s Hidden Risk: A Fading Income

The 100% Guaranteed Annuity (GA) solves for the longevity risk problem. With this type of annuity you exchange your capital for a predictable income stream you cannot outlive. It is an insurance contract with terms agreed upfront that cannot be changed.

Your capital is no longer yours to manage or leave as a legacy but you do get peace of mind that the payments will never stop while you are alive.

Even if you are not worried about leaving a legacy behind there is still a potential issue for you to consider though. Inflation risk.

When you buy this annuity the agreement will stipulate the income you receive and how that will be adjusted year after year. In this example we selected an annuity which increases by 5% per year.

But since inflation is assumed to be 7%, your income will not keep up with your real world expenses. Also known as a loss of purchasing power.

The model reveals that the GA fails to provide 100% of the required income from age 80 onwards. By age 85, it covers only 88% of your needs. At 90, that falls to 80%, and by age 100, your “guaranteed” income covers just 67% of your lifestyle costs.

You won’t run out of money, but you may run out of your income’s ability to cover your living expenses fully.

3. The Hybrid “Blend”: A superior system

This brings us to the most powerful finding from the analysis.

When you stop seeing this as an “either/or” choice you can potentially build a better solution to solve for both longevity and purchasing power risk.

The model tested a Blended Annuity where 40% of the initial capital (R4 million) was used to purchase a Guaranteed Annuity, with the remaining R6 million invested in a Living Annuity.

The results speak for themselves.

First, the blend provides 100% of the retiree’s required income all the way to age 95, improving on the  GA’s purchasing power problem and the LA’s longevity problem.

And what about your concerns over leaving a legacy behind?

After 30 years of providing an income, the Blended Annuity’s capital had grown to R17.3 million, more than four times the R4.1 million projected to be remaining in the pure Living Annuity portfolio. (As mentioned you do not get to leave any of the GA capital to beneficiaries).

Conclusion:

This analysis shows that an intelligent, blended approach is potentially a superior solution designed to mitigate the primary risks of both standalone strategies.

That could transform everything for you and make your tough decisions easier at this crucial time.

Lets chat if this is something you want to understand and potentially include in your own retirement planning transition.

By the way……. If you are still feeling a little overwhelmed and perhaps have even more questions as you approach retirement? Why not check out my RETIRE READY workshop designed to help you make the best decisions from a position of real knowledge. Find out more here: RETIRE READY  

Read More

Let’s change the ending…

You may not have the power to change where you are but you can change where you are going.